Rules
Old House Knob and Tube Insurance: How Coverage Is Decided
Old house knob and tube insurance: the four layers of rules that decide coverage, the file underwriters ask for, and the five routes that can keep a policy.
What to take away
- Underwriters drive most old house knob and tube insurance decisions. The National Electrical Code lets existing wiring stay in a one- or two-family home.
- Your file needs evidencean inspection report from a licensed electrician, dated photographs and a written plan for anything the carrier flags.
- State, municipal and private rules stack on each other, and the private layer is where refusals begin.
- Skipping the requirements has a concrete result. A carrier can cancel mid-term, and a claim traced to old wiring can be denied.
- Coverage stays open through specialty carriers, a certification, a partial rewire or an exclusion endorsement. An exclusion leaves the loss with you.
Insurers treat an old house as a documentation problem before they treat it as an electrical one. The wire behind your plaster has not changed. What changed is how carriers decide to accept the risk.
Who sets the rules on knob and tube
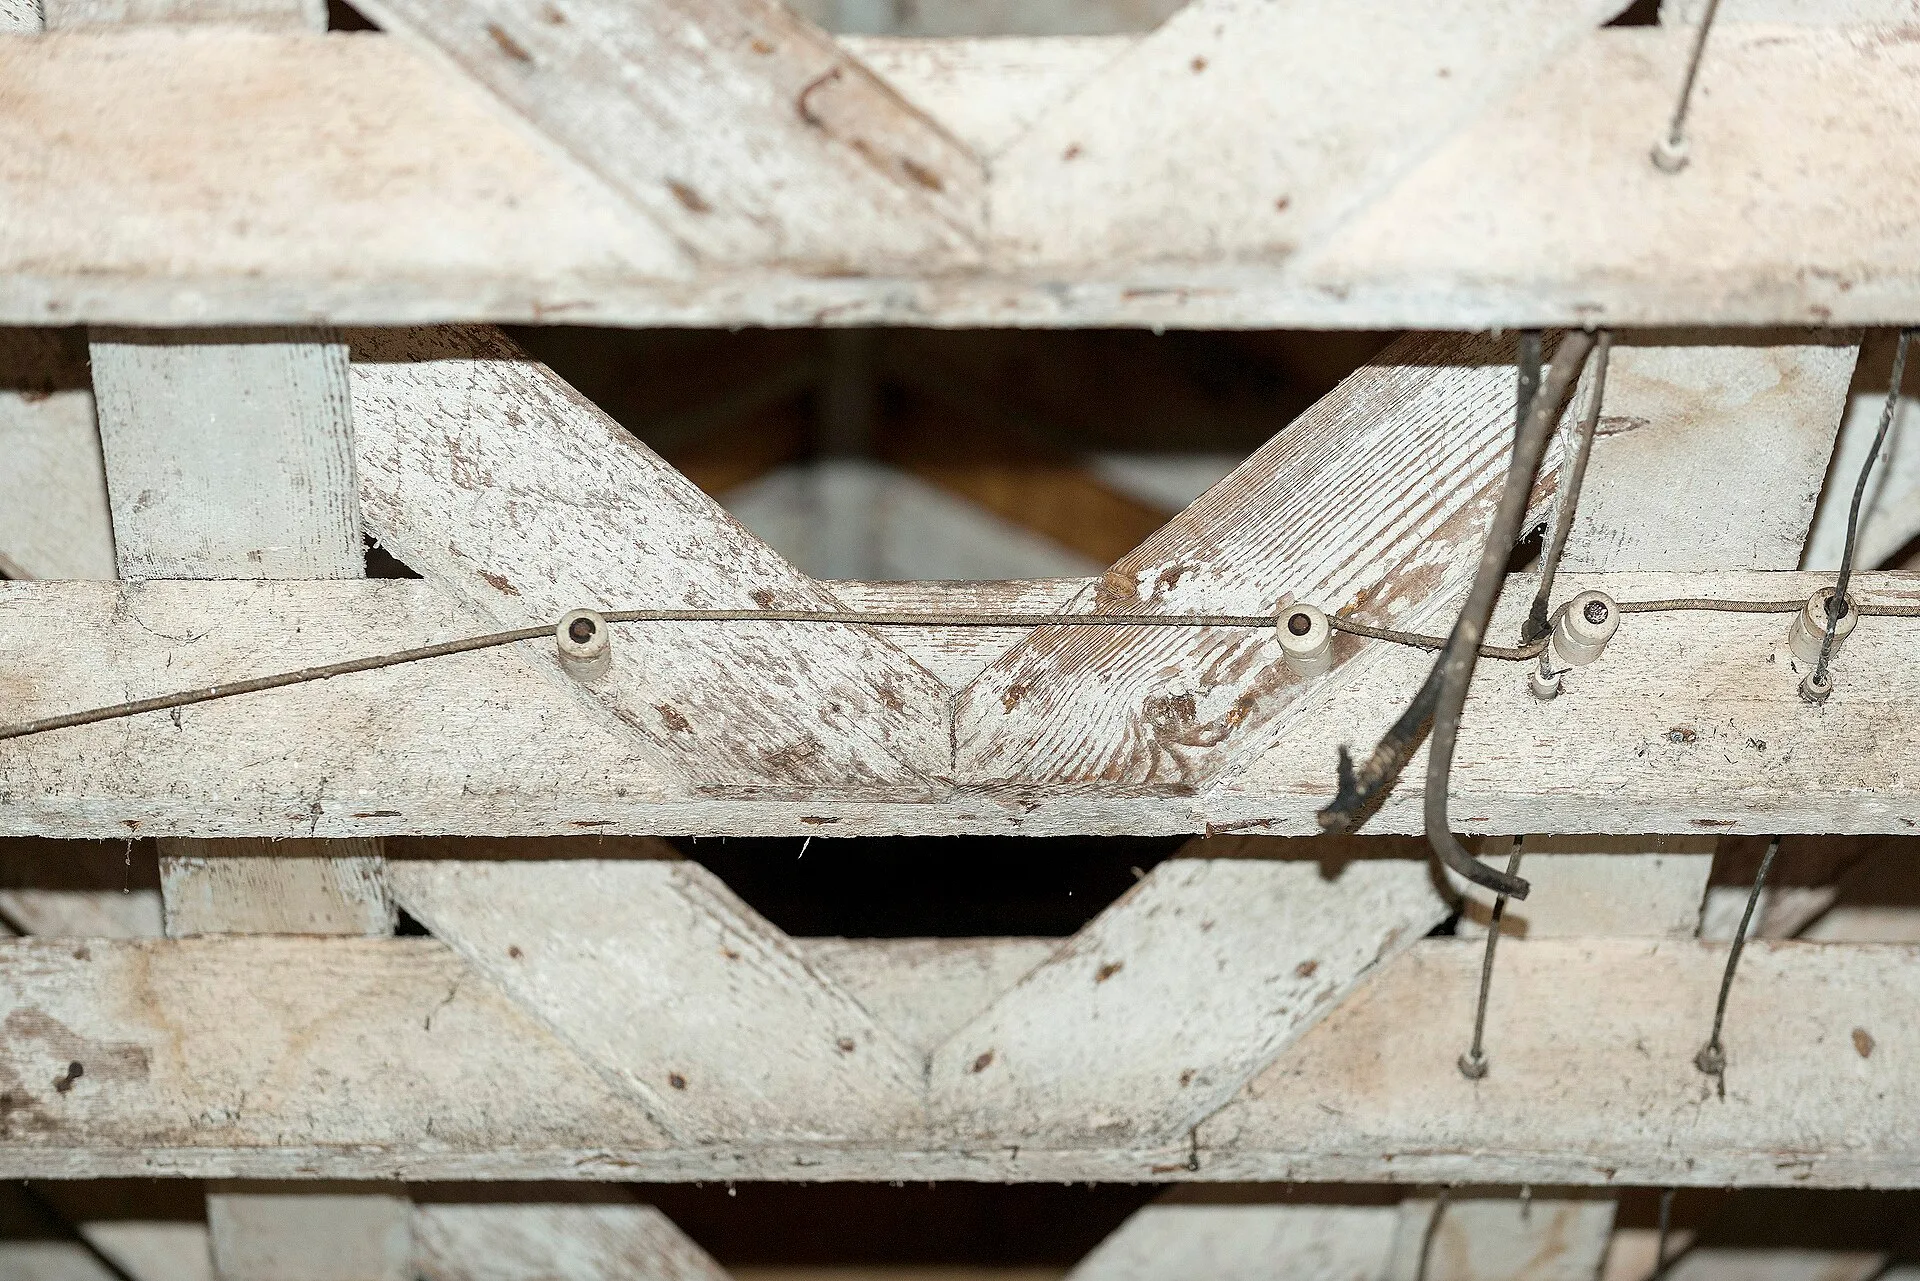
Four layers decide whether your wiring is insurable, and they rarely agree. Start with the code. Article 394 of the National Electrical Code covers concealed knob-and-tube wiring, and the code does not require removal of existing knob and tube in a one- or two-family dwelling. States adopt that code as law, as NFPA's National Electrical Code page explains.
Four Layers That Decide Insurability
Layer
- Model code
- State or local adoption
- State insurance dept.
- State regulator
- Municipal building dept.
- Local officials
- Private carrier
- Underwriter
Who enforces it
- Model code
- Existing knob and tube may remain
- State insurance dept.
- Cancellation notice, residual markets
- Municipal building dept.
- Permits, inspections, amendments
- Private carrier
- Decides whether to write the house
What it demands
- Model code
- State insurance dept.
- Municipal building dept.
- Private carrier
State insurance departments sit above the code, controlling cancellation notice periods and access to plans of last resort. California and New York both publish fire-risk underwriting guidance that reaches older wiring, and both run residual markets, the California FAIR Plan and the New York Property Insurance Underwriting Association.
Municipal building departments add permits, inspections and local amendments. That is where a partial rewire is examined in person. Unpermitted work from a previous owner surfaces at the same counter, so anyone who inherits a badly restored house should read the permit file first.
The fourth layer is private and refuses you: a carrier's underwriting guide decides whether it will write the house.
Who sets the rules
| Layer | Who enforces it | What it demands |
|---|---|---|
| Model code | State or local adoption | Existing knob and tube may remain in a one- or two-family home |
| State insurance department | State regulator | Notice periods and residual-market access |
| Municipal building department | City or county | Permits and inspection of new work |
| Carrier underwriting guide | Insurer | A replacement date, a certification or an exclusion |
What an insurer asks for before it will quote
Most carriers want the same file, and you can assemble it before you shop: an inspection report from a licensed electrician, dated photographs of the panel and the visible wiring, a written plan for anything the underwriter flags, and, where work has been done, the permit and inspection record from the municipal building department.
What Insurers Ask For
- Inspection reportpanel, meter base, accessible runs
- Dated photospanel interior, attic runs, splices
- Inspector's estimate of wiring installation date
- Scope and schedule for requested repairs
- Loss history via CLUE report
- Lead-safe work records if built before 1978
If the house was built before 1978, add lead-safe work records. Opening a wall for electrical work brings federal renovation rules into the job, and the Lead Paint Rules article explains what a contractor must hold before touching painted surfaces.
A certification letter is not a clear inspection
A certification says an electrician examined the accessible wiring and found it serviceable. It says nothing about what sits behind plaster, and it does not bind the carrier. Certification forms vary from one carrier to the next, so ask the underwriter to name the form it accepts, in writing, before anyone visits the house.
Florida is where the four-point inspection is standard practice, and Citizens Property Insurance Corporation, the state's insurer of last resort, asks for one on older homes. The report covers the roof, plumbing, heating and the electrical age in a single visit. Some carriers accept it; others insist on their own form. Ask for the underwriting guideline in writing when a phone answer sounds vague.
What happens when you skip the requirements
Non-compliance costs you the policy, not a fine. If your application states the house has no knob and tube and an adjuster later traces a fire to an old splice, the carrier can treat that as material misrepresentation and deny the claim. Carriers also cancel at renewal, and a servicer then force-places coverage that excludes wiring nobody has inspected.
The choice between disclosing old wiring and saying nothing is the tempting shortcut. Our comparison sets out what each one really leaves you holding. Correcting unpermitted work later opens walls, which is where the next set of rules starts.
Getting insured when the wiring stays
Five routes exist, and they are not equal. The cleanest is a specialty or regional carrier that writes older housing; your state insurance department's list of licensed writers is where to find the ones active in your area. Next comes a documented partial rewire, where an electrician replaces the runs an underwriter objects to and the rest stays. A certification satisfies some carriers, an exclusion endorsement satisfies many, and a full rewire satisfies nearly all.
Five Routes to Coverage
Route
- Specialty carrier
- Writes older housing
- Partial rewire
- Replace objected runs
- Certification
- Electrician examines wiring
- Exclusion endorsement
- Wiring risk excluded
- Full rewire
- Replace all wiring
What it involves
- Specialty carrier
- Cleanest
- Partial rewire
- Documented
- Certification
- Some carriers
- Exclusion endorsement
- Many carriers
- Full rewire
- Nearly all
Carrier acceptance
- Specialty carrier
- Partial rewire
- Certification
- Exclusion endorsement
- Full rewire
If the partial rewire disturbs painted surfaces in a pre-1978 house, the EPA's renovation, repair and painting program explains who must be certified to do the work.
A carrier that writes the policy with a wiring exclusion has not accepted the risk. It has handed the loss back to you.
Where a carrier demands replacement, the repairs rarely stay inside one circuit, and our breakdown of what restoration repairs cost covers the work that follows.